Sydney had one of its biggest months of the year in October 2026. Industrial leasing hit an all-time quarterly record, two of the CBD's best-known towers changed hands at firmer prices, a fashion empire paid $87 million for an Alexandria warehouse campus and the data centre build-out kept pulling in billions. All of it is happening with the cash rate at 4.60 per cent and a fifth rate rise for the year tipped for 3 November.
This October 2026 update rounds up the deals, leases and projects that shaped the Sydney commercial and industrial market this month, what the latest numbers say and what to watch as the year closes.
Sydney commercial property in October 2026 at a glance
- Industrial vacancy: 5.4 per cent at the end of September, down from 5.8 per cent (JLL, buildings over 5,000 sqm)
- Industrial take-up: a record 630,500 sqm in the September quarter, about 23 per cent above the city's previous high
- Pre-commitments: around 417,700 sqm of that leasing was pre-committed space
- Industrial rents: flat, up just 0.1 per cent over the quarter
- Biggest office deal: OUE REIT buying Ping An's 50 per cent of Salesforce Tower, 180 George Street, for about $864 million
- Biggest industrial sale: 19 O'Riordan Street, Alexandria, $87 million to the White Fox Boutique founders
- Biggest financing: a $4.25 billion green loan for AirTrunk's SYD3 data centre at Eastern Creek
- Interest rates: cash rate 4.60 per cent, September CPI 4.3 per cent, a rise to 4.85 per cent widely expected on 3 November
Sydney industrial: a record quarter for leasing
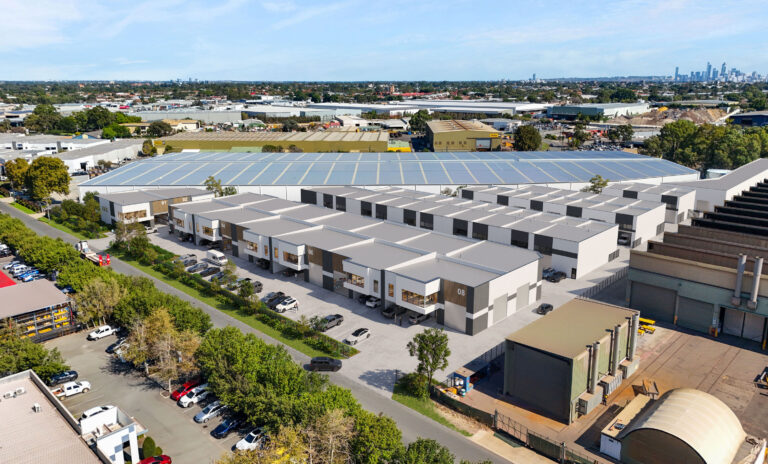
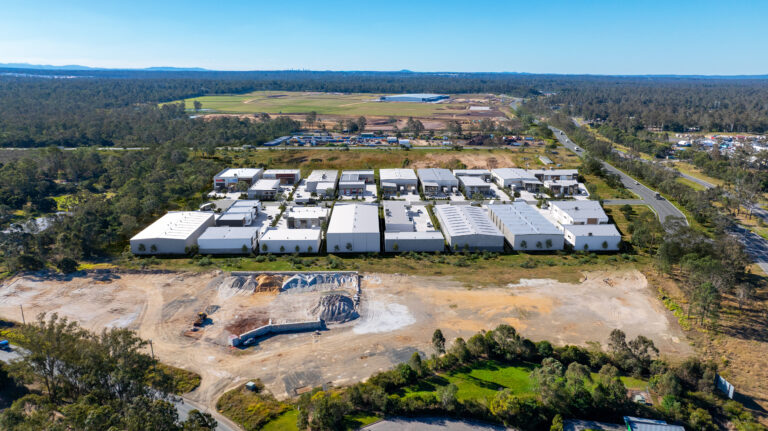
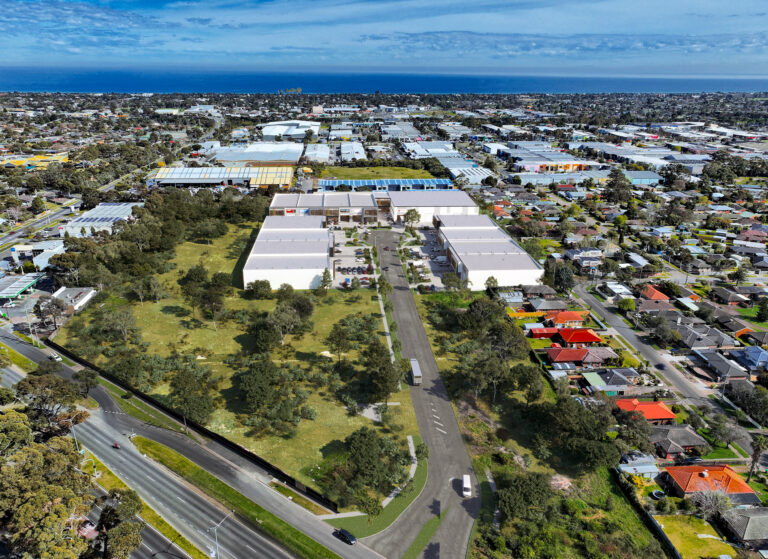
Sydney still has the highest industrial vacancy of the five big capitals, but it is now falling. JLL's Q3 report shows vacancy easing from 5.8 to 5.4 per cent while gross take-up reached 630,500 sqm. That is a record for the city and well ahead of the previous high set in mid-2020.
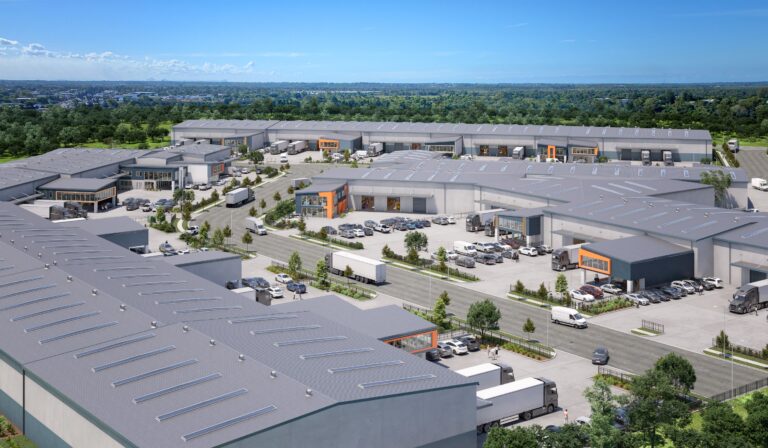
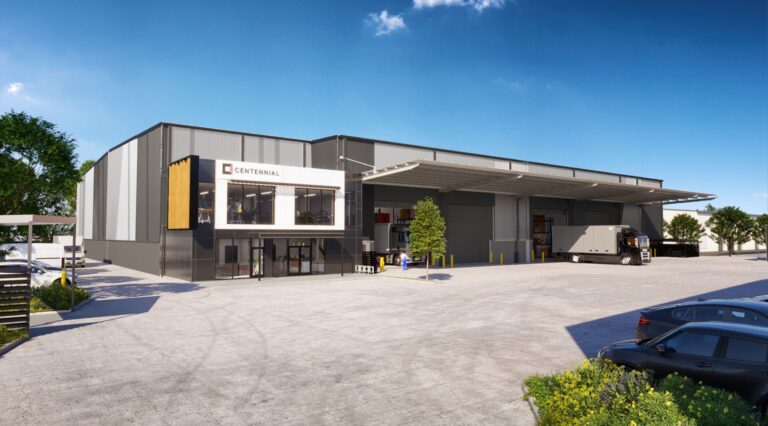
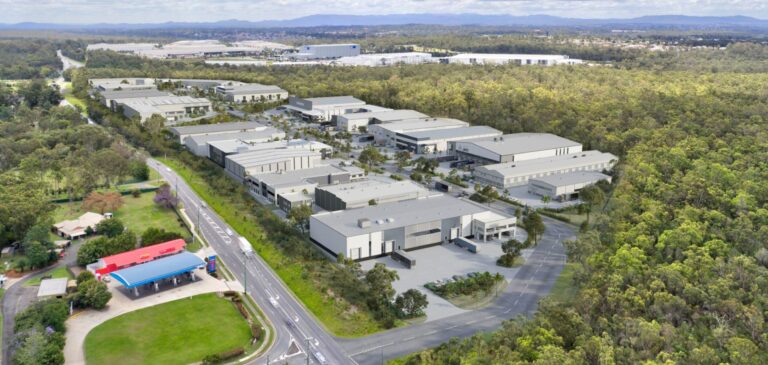
Most of that was pre-leasing. Around 417,700 sqm was committed before buildings were finished, which shows where the action is. Third-party logistics groups, big retailers and the contractors and suppliers feeding the data centre boom are locking in new, high-clearance space early. Rents were essentially flat over the quarter, so tenants with flexibility can still negotiate, particularly on older stock in the outer west.
Bought and sold: Sydney's October deals
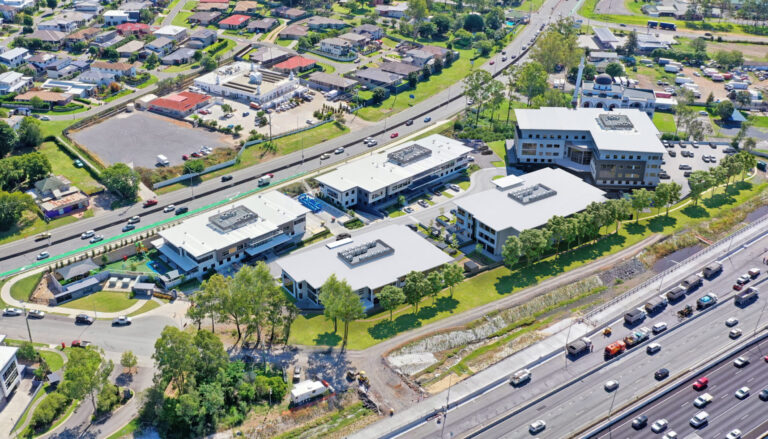
Salesforce Tower, 180 George Street – about $864 million (50 per cent). Singapore-listed OUE REIT has agreed to buy Ping An Real Estate's half share of the city's tallest office building, lifting its stake from 19.9 to 69.9 per cent. The deal values the 55-level Circular Quay tower at about $1.73 billion on a 5.75 per cent capitalisation rate and is subject to FIRB approval. Colliers and JLL handled it.
5 Martin Place – $394 million (50 per cent). The Mirvac Wholesale Office Fund bought Cbus Property's half share at a 5.75 per cent yield, implying a value of $788 million for the 19-level tower. Cbus bought the same stake in 2024 at a 6.1 per cent yield, so the building has gained roughly a third in value in two years. It is one of the clearest signs yet that pricing for top-end CBD office has turned the corner.
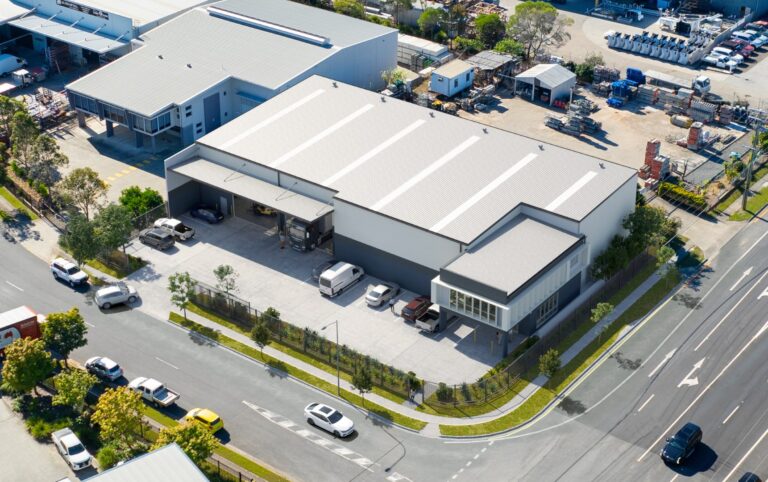
19 O'Riordan Street, Alexandria – $87 million. White Fox Boutique founders Daniel and Georgia Contos bought the 1.31-hectare warehouse and office campus held by the Hendler family, behind brand distributor True Alliance, since 1992. The site has about 11,437 sqm of improvements, 134 metres of frontage and E3 zoning with an FSR of 2.5:1. Colliers ran the sale. It shows what owner-occupiers will pay for large freehold sites close to the CBD and the airport.
11 Stanton Road, Seven Hills – $18.3 million. Pipeclay Lawson bought a 1.2-hectare holding with three older industrial buildings on a 15-year triple net leaseback to Master Builders Solutions. The initial yield was 5.68 per cent and the land rate about $1,488 per sqm. CBRE sold it by expressions of interest.
Smaller western deals. Taiwanese-listed Beyond Limited bought a warehouse and office asset at 21–23 Elizabeth Street, Wetherill Park, for $10 million through CBRE. A timber processing facility at 44–48 Links Road, St Marys, sold for more than $12 million. Both point to steady demand for functional sheds under $20 million.
On the market: Australia Post and Doyles
Australia Post logistics sites – above $320 million. Colliers is selling 10–24 Ralph Street, Alexandria and 51 Sargents Road, Minchinbury with long-term leasebacks to Australia Post. Together they cover about 126,500 sqm of land and 52,295 sqm of buildings, with net income of about $17.6 million a year and fixed 3.25 per cent annual reviews. Expressions of interest close on 6 November.
Doyles on the Beach, 11 Marine Parade, Watsons Bay – around $70 million hoped for. The Doyle family has listed the famous waterfront restaurant and the adjoining 2 Cliff Street for the first time in its 141-year history. The consolidated site is about 2,504 sqm with 29 metres of frontage to Watsons Bay Beach and SP3 Tourist zoning. HTL Property's international expressions of interest campaign closes on 25 November.
Data centres: billions keep flowing west and north-west
AirTrunk has secured a $4.25 billion green loan to finish SYD3 at Eastern Creek. The facility is backed by 32 Australian and international lenders, with 14 banks underwriting it. The 8.3-hectare campus is due for completion in mid-2028. It is one of the largest construction debt packages written for any Australian property this year.
In the north-west, GreenSquareDC switched on 15MW of AI-ready capacity at SYD1, 3 Brookhollow Avenue, Norwest. The 1995-era IBM building was turned into a liquid-cooled GPU hall in eight months and the whole first stage is leased to Sharon AI. An 80MW second stage is working through the State Significant Development process.
Further afield, CDC Data Centres lodged plans for a $15 billion, 1.4-gigawatt campus at 216 Ashfords Road, Gregadoo, near Wagga Wagga. The lesson for Sydney landowners is that power and grid access now decide where these projects go. The search for capacity is spreading well beyond the metro area.
Office: the top end is firming
The two big CBD deals this month tell the same story. Buyers paid 5.75 per cent yields for both Salesforce Tower and 5 Martin Place, which is firmer than the pricing seen in 2024 and early 2025. Prime, well-located towers with strong tenants are drawing both offshore and domestic capital.
The picture is very different for older secondary buildings. Sydney CBD vacancy was 13.3 per cent in the Property Council's July count and much of the empty space sits in B-grade stock. Owners there are weighing refurbishment, conversion or a sale at a lower price. Rising interest rates make funding a repositioning harder.
Interest rates and what they mean for Sydney
September's CPI came in at 4.3 per cent and the trimmed mean rose 1.0 per cent over the quarter, ahead of the RBA's forecast. Most economists now expect the cash rate to rise from 4.60 to 4.85 per cent on Tuesday 3 November, the fifth rise this year.
So far, the big end of the market is looking through it. Super funds, REITs and offshore buyers with low gearing did the major deals this month. Leveraged private buyers are the ones feeling the squeeze, which is why well-priced sub-$20 million assets with secure income are still drawing competition while debt-funded bidders thin out.
Precinct watch
- South Sydney (Alexandria, Mascot, Botany): the $87 million O'Riordan Street sale and the Australia Post campaign show how scarce and valuable large freehold sites close to the CBD and airport have become.
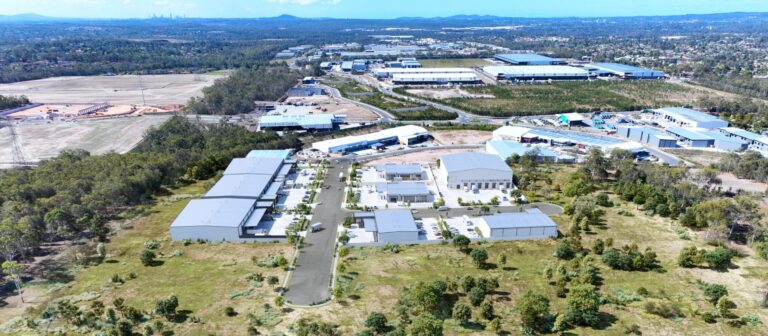
- Outer west (Eastern Creek, Kemps Creek, Erskine Park): home to most of the record pre-leasing and the AirTrunk SYD3 build.
- Central west (Seven Hills, Wetherill Park, Smithfield): steady investor and owner-occupier demand for older sheds with good motorway access.
- North-west (Norwest, Castle Hill): business park buildings are being reimagined for data and technology users.
- Inner west (Tempe, Marrickville, Sydenham): government surplus land is being sold to developers, with industrial strata planned near the Metro.
What this means for owners, developers and occupiers
- Income sells. Long leasebacks with fixed or CPI reviews are drawing yields in the mid-5s. Present the lease clearly and the buyer pool widens.
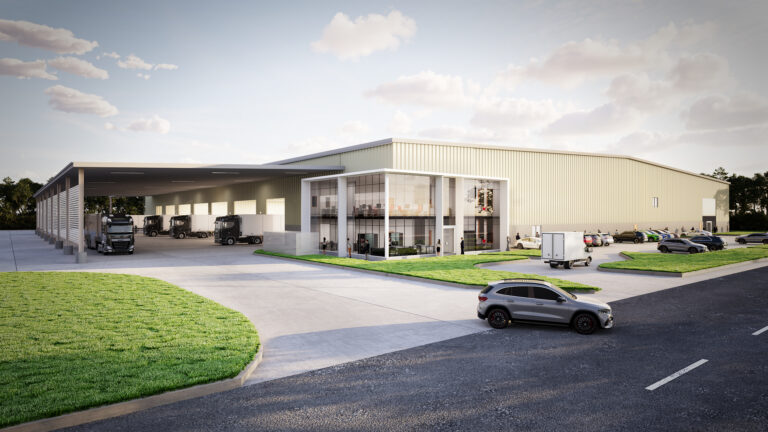
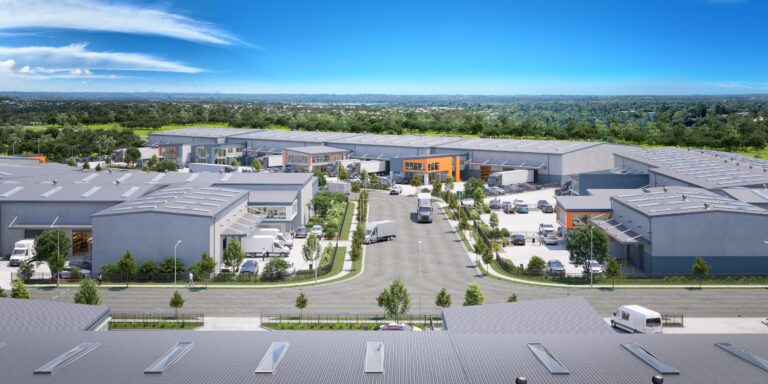
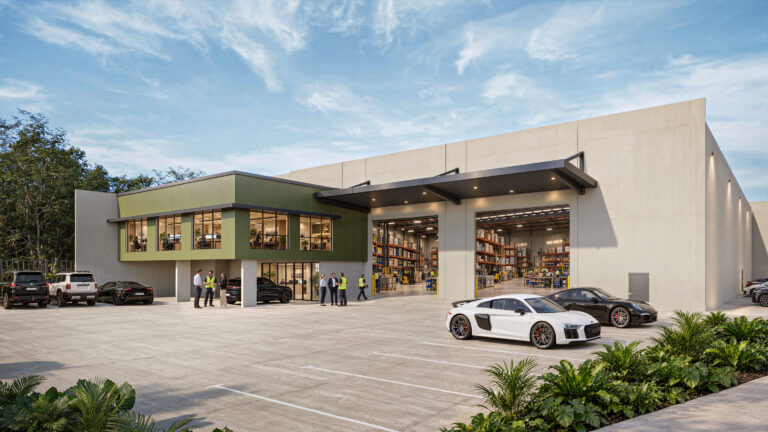
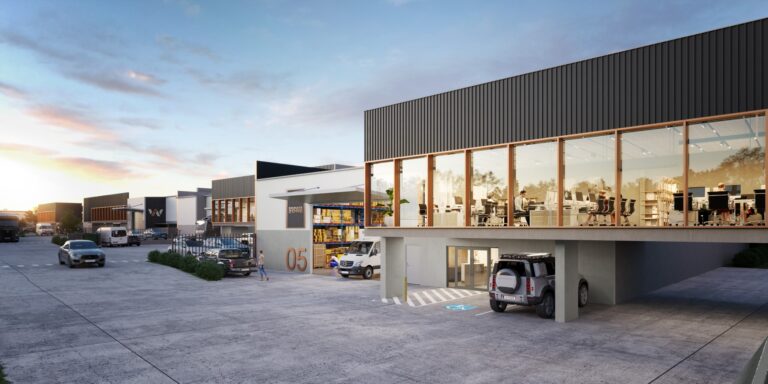
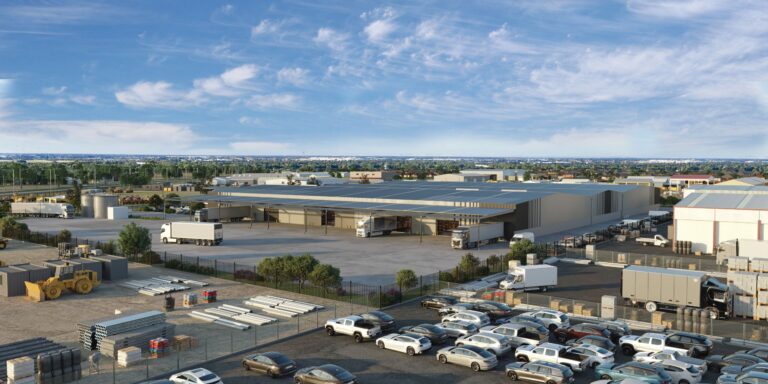
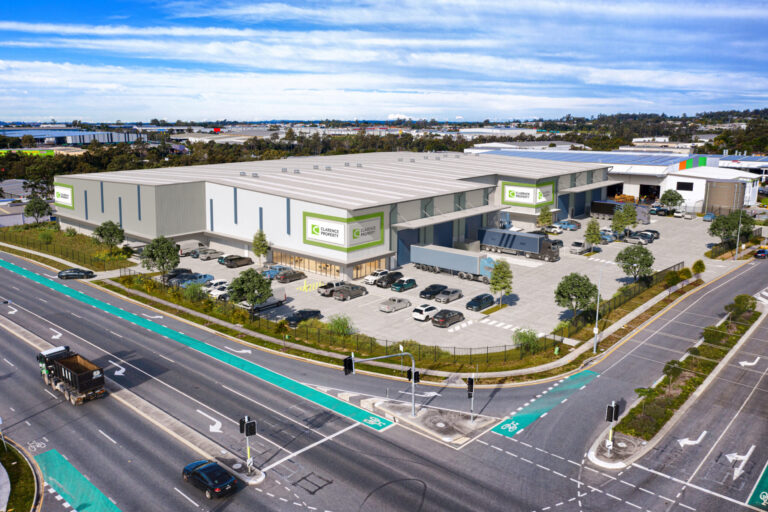
- Pre-leasing rewards developers who can show the finished product. With record pre-commitments, the projects winning tenants are the ones that help occupiers picture the building, the yard and the truck flow before construction starts.
- Owner-occupiers are a serious buyer group. Campaigns for well-located sheds should reach operating businesses directly, not only investors.
- Power is a selling point. Any site with real electrical capacity or a clear path to it should say so up front.
What to watch in November
The RBA decision on 3 November comes first, followed by the Australia Post expressions of interest closing on 6 November and the Doyles campaign on 25 November. Watch for FIRB approval of the Salesforce Tower deal and for whether record pre-leasing keeps pulling Sydney industrial vacancy down towards 5 per cent before the end of the year.