
QIC has sold a 50 per cent stake in Watergardens, the major regional shopping centre in Melbourne's north-west, to the Commonwealth Superannuation Corporation (CSC) for $480 million. The price is reported to be slightly above the stake's book value of around $470 million, a clear sign that institutional money is back in big regional retail.
The deal is one of the largest retail transactions in Australia this year. It also continues a trend we are seeing across the market: super funds and wholesale investors are building up retail positions after several years of avoiding the sector.
The deal at a glance
- Asset: Watergardens, 399 Melton Highway, Taylors Lakes VIC
- Interest sold: 50 per cent, held by the QIC Town Centre Fund
- Price: $480 million
- Book value: around $470 million
- Buyer: Commonwealth Superannuation Corporation, with GPT Group as investment manager
- Seller: QIC. Sister vehicle QIC Property Fund keeps the other half.
- Ongoing management: QIC stays on as property manager
- Agent: Colliers
A very big piece of land
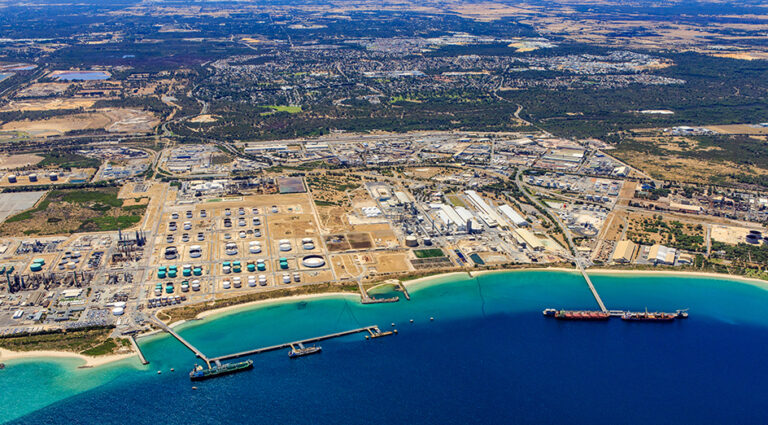
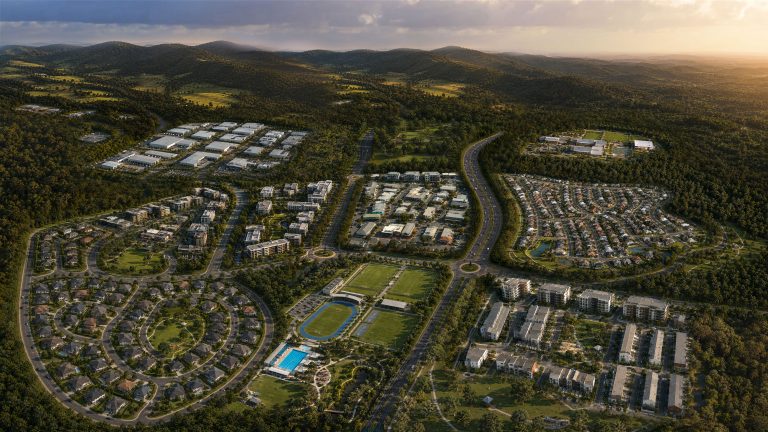
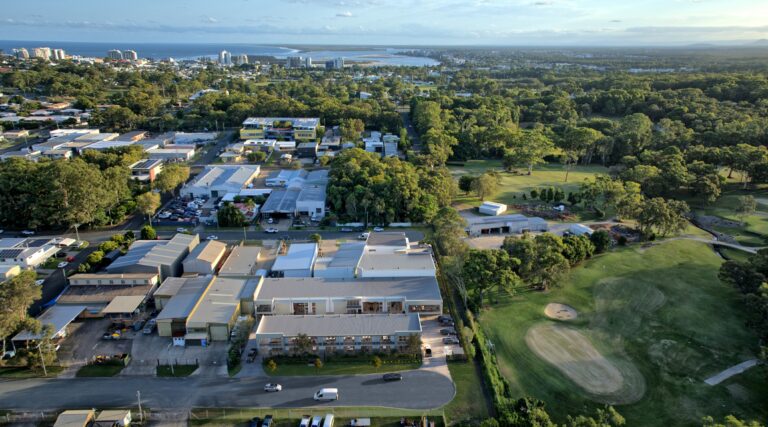
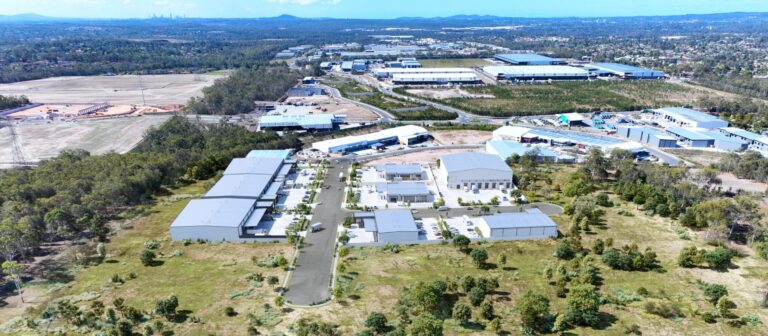
Watergardens is often described as Australia's largest single-title retail landholding. The site covers about 47.9 hectares, roughly 20 kilometres north-west of the Melbourne CBD.
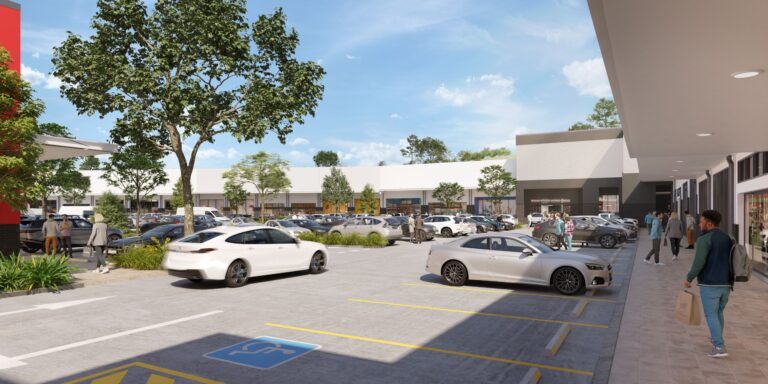
The centre has around 71,226 sqm of retail floor space across 206 tenancies. Its anchors are Woolworths, Aldi, Kmart, Big W and Hoyts. The landholding also includes the Watergardens Super Centre, an 86-room hotel leased to Quest, mini-majors, kiosks and pad sites. QIC reports about 11.7 million visits a year.
Transport is a big part of the appeal. Watergardens railway station sits on the south-western edge of the site and Sydenham station is just off its north-western corner. In one of Melbourne's fastest-growing corridors, that kind of public transport access is hard to replicate.
Thirty years of growth and reinvestment
QIC developed Watergardens in 1995 and has kept investing in it. More than $110 million has gone into capital works and remixing since 2019, including the Town Square and South Mall precincts. Those upgrades are part of why the centre is attracting a long-term owner at a premium to book value.
QIC has also flagged the wider precinct for staged mixed-use development, including apartments and offices. With almost 48 hectares under one title, the land offers a long-term development pathway as well as retail income. Buyers are increasingly paying for that kind of optionality.
Watergardens has changed hands in parts before. In 2021, Harvey Norman bought the neighbouring Watergardens Homeplace showroom centre from QIC funds for $97 million.
Why CSC is buying
CSC manages retirement and pension schemes for former federal government employees and Australian Defence Force members. Its property holdings include a mandate of around $2.6 billion managed by GPT Group, which already includes a 50 per cent interest in Indooroopilly Shopping Centre in Brisbane and offices such as 101 Collins Street in Melbourne. Watergardens takes that mandate close to $3 billion.
For a long-term pension investor, a dominant regional centre has some clear advantages:
- non-discretionary anchors such as supermarkets and discount department stores that keep foot traffic steady
- a growing, family-heavy catchment in Melbourne's north-west
- a huge land bank with potential for higher-density uses over time
- an experienced co-owner and manager staying in the asset
Why QIC is selling, and keeping half
QIC began looking for an investment partner for the Town Centre Fund's share in late 2025. Selling at or above book value lets the fund crystallise value and recycle capital. Because the QIC Property Fund keeps the other half and QIC stays on as manager, the centre's day-to-day strategy should not change.
Half-stake sales like this have become a common way for large owners to manage exposure without giving up control of operations. It is the same structure we covered in Sydney this week, where Cbus Property sold half of 5 Martin Place to Mirvac's wholesale office fund.
The retail comeback is real, but selective
Retail spent several years as the sector institutions avoided, as online shopping grew and the pandemic shut centres down. That view has shifted. Non-discretionary centres held up, new retail supply has been minimal, and rents in well-run centres have stabilised. Investors who stayed underweight retail are now buying back in.
Recent activity backs that up. In August, Cbus Property paid around $1.3 billion for half shares in two regional centres in Queensland and Western Australia. This week, HMC Capital agreed to buy Coburns Central, a Woolworths-anchored neighbourhood centre in Melton West, for $49 million at a 5.5 per cent yield. Both large and small convenience-based retail are trading.
The common thread is quality and catchment. Centres with strong anchors, good access and room to evolve are getting competitive interest. Tired centres in flat catchments are still hard to sell.
What it means for owners and developers
- Land is part of the value. Large retail sites with mixed-use potential are being valued on future density as well as today's income.
- Reinvestment pays off. Watergardens' $110 million upgrade program helped it sell at a premium.
- Transport access counts. Train stations at the door add long-term value in fast-growing outer suburbs.
- Tell the precinct story. Where the future of a site lives in plans and masterplans, clear visuals and campaign material help investors see the upside they are paying for.
What to watch next
Watch whether QIC moves ahead with the mixed-use plans for the wider Watergardens precinct now that it has a new co-owner. Watch whether more half-stake retail deals follow as super funds rebalance their portfolios. And watch whether yields on prime regional centres firm further as competition for limited stock increases.
For now, the Watergardens sale is a strong vote of confidence in Melbourne's western growth corridor, and in the idea that the best regional shopping centres are long-term infrastructure assets.